

Uche Cecil Izuora
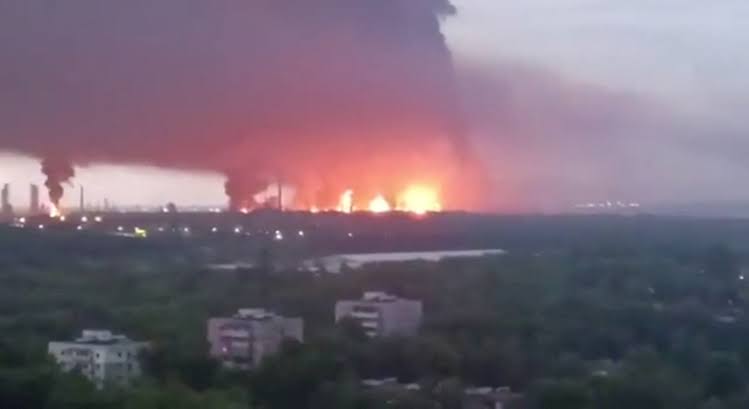
Renewed attacks on Russian energy infrastructure increased uncertainty across petroleum markets.
Global oil prices climbed toward $110 per barrel Friday, reaching their highest levels since May as concerns about Middle Eastern supply disruptions.
Brent crude futures reached $109.86 per barrel during the session, while West Texas Intermediate (WTI) closed at $101.41. The advance reflects growing concerns about the reliability of international petroleum supplies and the ability of producers to maintain deliveries through major transportation corridors.
For energy companies, the latest price increase creates different financial implications across the industry, particularly for upstream producers, refiners, and transportation operators.
Higher crude prices generally support revenue and operating cash flow for exploration and production companies. Producers with established production, manageable operating costs, and limited hedging exposure may benefit most directly from sustained price strength.
However, elevated commodity prices do not automatically translate into higher capital spending. Companies must evaluate whether current market conditions are likely to persist before committing additional investment to drilling programs, acquisitions, or infrastructure expansion.
The current rally is being driven partly by renewed concerns surrounding the Strait of Hormuz, where attacks on commercial shipping continue to complicate petroleum exports from the Middle East.
Saudi Arabia also reported intercepting a ballistic missile directed toward the Red Sea port of Yanbu, although authorities indicated that the incident caused no damage.
Meanwhile, Ukrainian strikes on Russian energy infrastructure have raised additional questions about the country’s refining capacity and ability to maintain petroleum product exports.
These developments come as governments pursue measures intended to improve fuel availability, including emergency petroleum reserve releases and changes to restrictions affecting certain Russian diesel shipments.
For refiners, higher crude acquisition costs present a different financial challenge. Profitability depends on whether gasoline, diesel, and other refined product prices increase sufficiently to offset more expensive feedstocks.
Refineries with reliable operations and access to competitively priced crude may be better positioned to manage these conditions.
Midstream companies and export terminal operators could also experience changing demand as international buyers adjust crude sourcing and transportation arrangements.
Higher oil prices may support activity across producing regions, but elevated freight rates and shipping insurance costs can reduce the competitiveness of barrels delivered to distant markets.
For investors, the durability of the current rally is more important than any individual price milestone.
A sustained period of higher crude prices could strengthen producer balance sheets, support shareholder distributions, and improve the economics of selected development projects.
Conversely, a rapid improvement in regional security or transportation access could reduce the geopolitical premium embedded in current prices.
The next indicators to watch include petroleum flows through the Strait of Hormuz, Russian refinery operations, U.S. crude inventories, tanker freight rates, and changes in refining margins.
Oil’s move toward $110 underscores the importance of evaluating energy investments across the entire supply chain, where higher commodity prices can create both financial opportunities and operating challenges